Matt Evans
Head of Underwriting
Matt Evans, Head of Underwriting at LiveMore.
Matt Evans · Head of Underwriting
I've been underwriting for over 20 years. In that time, I've seen most versions of "computer says no." What we've built at LiveMore over the past six years is, I think, genuinely different. Not because we take more risk, but because we take the time to understand it properly before making a decision.
The honest answer is culture - at a lot of specialist lenders, underwriting becomes a filter. It's there to say no quickly, because no is easy and yes takes work. LiveMore was built the opposite way round, our starting point on every case is "how can we do this," not "why can't we."
That means our underwriters aren't just processing applications against a rigid checklist. They're empowered to operate in the grey areas of our policy where a case genuinely warrants it, and they're mandated to make that decision themselves. There's no committee sitting behind them second-guessing every file. When a broker speaks to one of our underwriters, they're speaking to the person who can actually say yes.
A broker recently brought us a large loan case that had been declined elsewhere. The issue wasn't affordability, it was how the client was drawing income from their own business. There were inconsistencies in the way that money was being released, and other lenders weren't willing to get into the detail to understand why.
The broker booked a call with our Hero Hotline, genuinely as something of a last resort. We went through the full business structure and company accounts together on the call. It's a technical conversation, there's no getting around that, but by the end of it we had a way forward we could put in writing there and then. No back and forth over email, no waiting a week for a decision that could have been made on the spot.
That's the kind of outcome we want every Hero Hotline call to deliver.
In my experience, it usually comes down to one of two things:
At LiveMore, our underwriters have specialist lending backgrounds and the mandate to make decisions themselves. That combination is what lets us work in the detail rather than around it.
There's a common misconception that LiveMore only lends to people at or approaching retirement. In practice, a large proportion of the complex, higher value cases we see involve people in their 40s who draw income from their own business in a non-traditional way. That's not unusual, and it's not a problem for us - it's exactly the kind of case our underwriting approach is built for.
The common thread isn't age, it's complexity and a willingness to actually understand it rather than decline on sight.
Book a call with our underwriting team before you write the case off, that's genuinely my advice.
The feedback we've had since launching the Hero Hotline has been overwhelmingly positive, and it's become one of the things I'm proudest of at LiveMore. Come to us with the detail. Challenge us with it - we're not afraid of complexity, and we'd rather work through it with you on a call than have you assume the answer is no before you've asked the question.
Head of Underwriting
Matt Evans, Head of Underwriting at LiveMore.
Later-life lending insight for intermediaries, straight to your inbox.
By subscribing you consent to LiveMore sending you our insights and updates by email. We'll only use your email address for this purpose. You can unsubscribe at any time using the link in every email. See our Privacy Policy for how we handle your data.
When LiveMore brought together industry leaders for the Later Life Lending is Dead. Or Is It? panel at the RSA, one message came through loud and clear: the way we talk about lending may need to change.
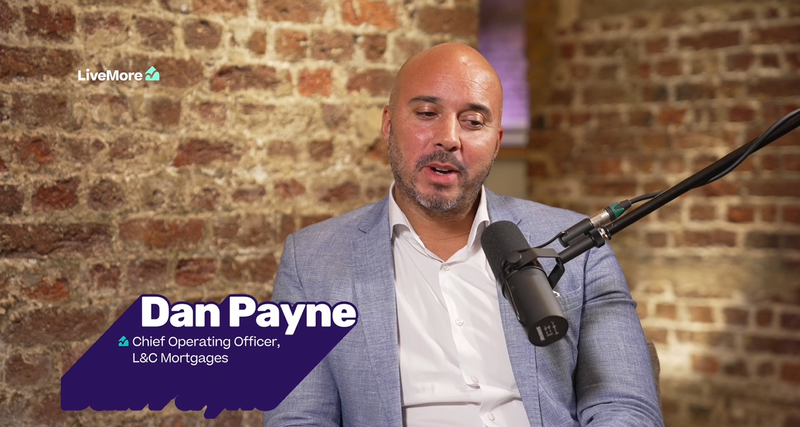
In this episode of Living More, Dan Payne, COO of L&C Mortgages, shares his key takeaways from LiveMore's RSA panel discussion, discussing the role of education and technology in delivering more holistic advice, the importance of understanding customer circumstances, and the future of the mortgage industry.

Watch our LiveMore Midlife Mortgage Crisis panel discussion, as our experts discuss what 'later life lending' even means when millions of customers in their 40s, 50s and 60s are now borrowing beyond retirement.